
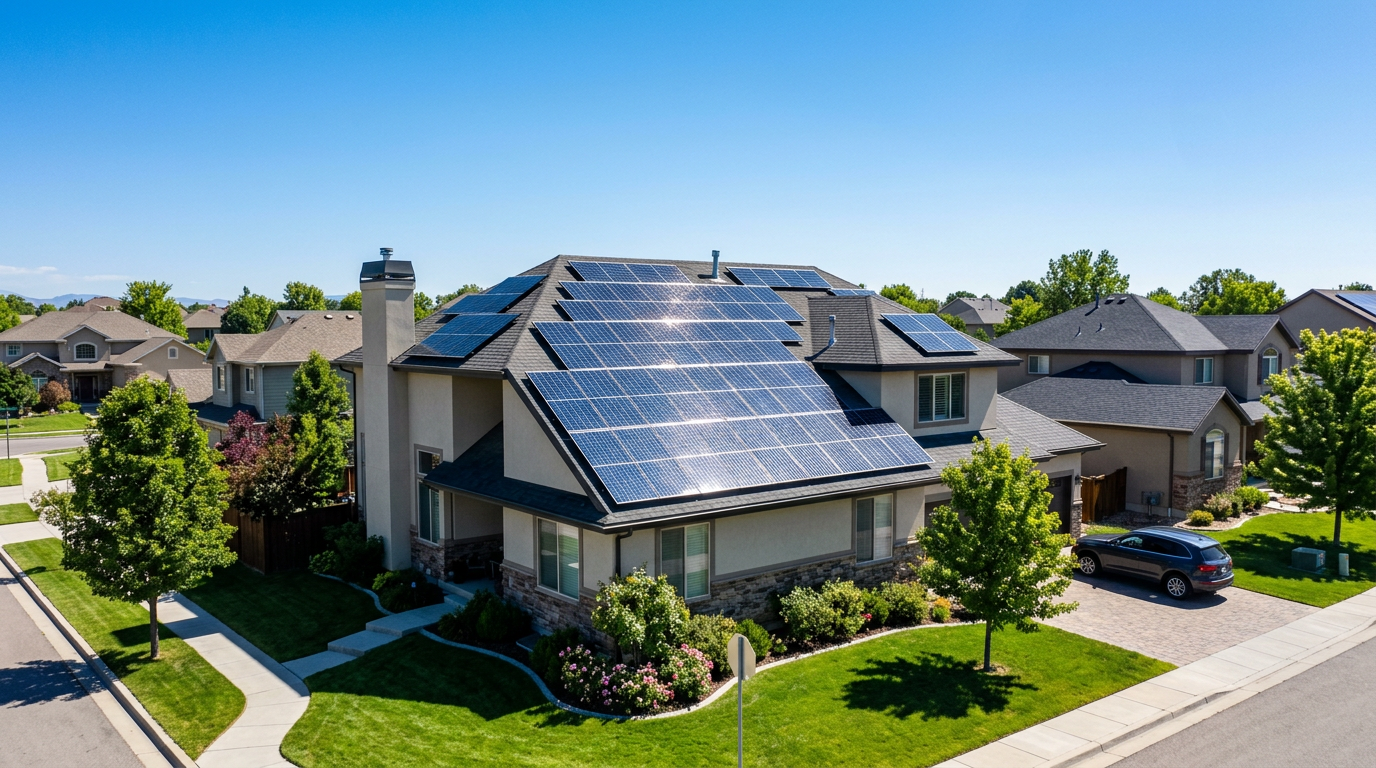
- System size: Measured in kilowatts, this should match your home’s energy needs and roof space
- Panel brand and model: Not all panels perform the same, even if they look similar on paper
- Inverter type: String inverters, microinverters, and power optimizers each have trade-offs
If you’re shopping for home solar, the quote is only the starting point. Two proposals can look similar on price and still be very different in equipment quality, contract terms, and long-term value.
Before you sign, it helps to compare solar quotes the way a careful buyer would: line by line, not just by monthly payment.
→ Energy Revolution System — free, takes about 60 seconds.
This guide focuses on what to check in a solar proposal so you can make a fair comparison and avoid surprises later. It’s especially useful if you’ve received multiple offers and aren’t sure why one seems much cheaper than the others.
Start with the basics: what the quote actually includes
A useful solar quote should clearly identify the equipment, system size, and services included. If a proposal is vague, ask for a revised version before you go further.
- System size: Measured in kilowatts, this should match your home’s energy needs and roof space.
- Panel brand and model: Not all panels perform the same, even if they look similar on paper.
- Inverter type: String inverters, microinverters, and power optimizers each have trade-offs.
- Battery storage: If included, note the battery model, usable capacity, and backup limitations.
We go deeper on this in our solar & energy guide — worth a read before you decide anything.
It’s also worth asking whether the quote includes removal and reinstallation costs for a future roof replacement. Some homeowners only learn about those expenses after the contract is signed.
Don’t compare monthly payments without checking the contract structure
→ See what you could be approved for — free, takes about 60 seconds.
Solar offers are often presented as a lease, loan, power purchase agreement, or cash purchase. A low monthly payment may look attractive, but the structure matters as much as the number itself.
If the quote is for a loan
Look beyond the payment amount. Ask about the interest rate, loan term, dealer fees, prepayment rules, and whether the payment changes over time. A longer term may lower the monthly bill but increase total cost.
If an offer includes an introductory rate or deferred interest, make sure you understand when and how that changes.
Sources & further reading
This article is for general information only and is not professional financial, legal, or medical advice.
Tom Bishop — Home & Safety Editor
Tom covers home security, improvement, and energy topics, comparing options on cost, reliability, and real-world performance so homeowners can decide with confidence.
Updated August 2026